Cómo Calificar para un Short Sale en Florida

Cómo Calificar para un Short Sale en Florida

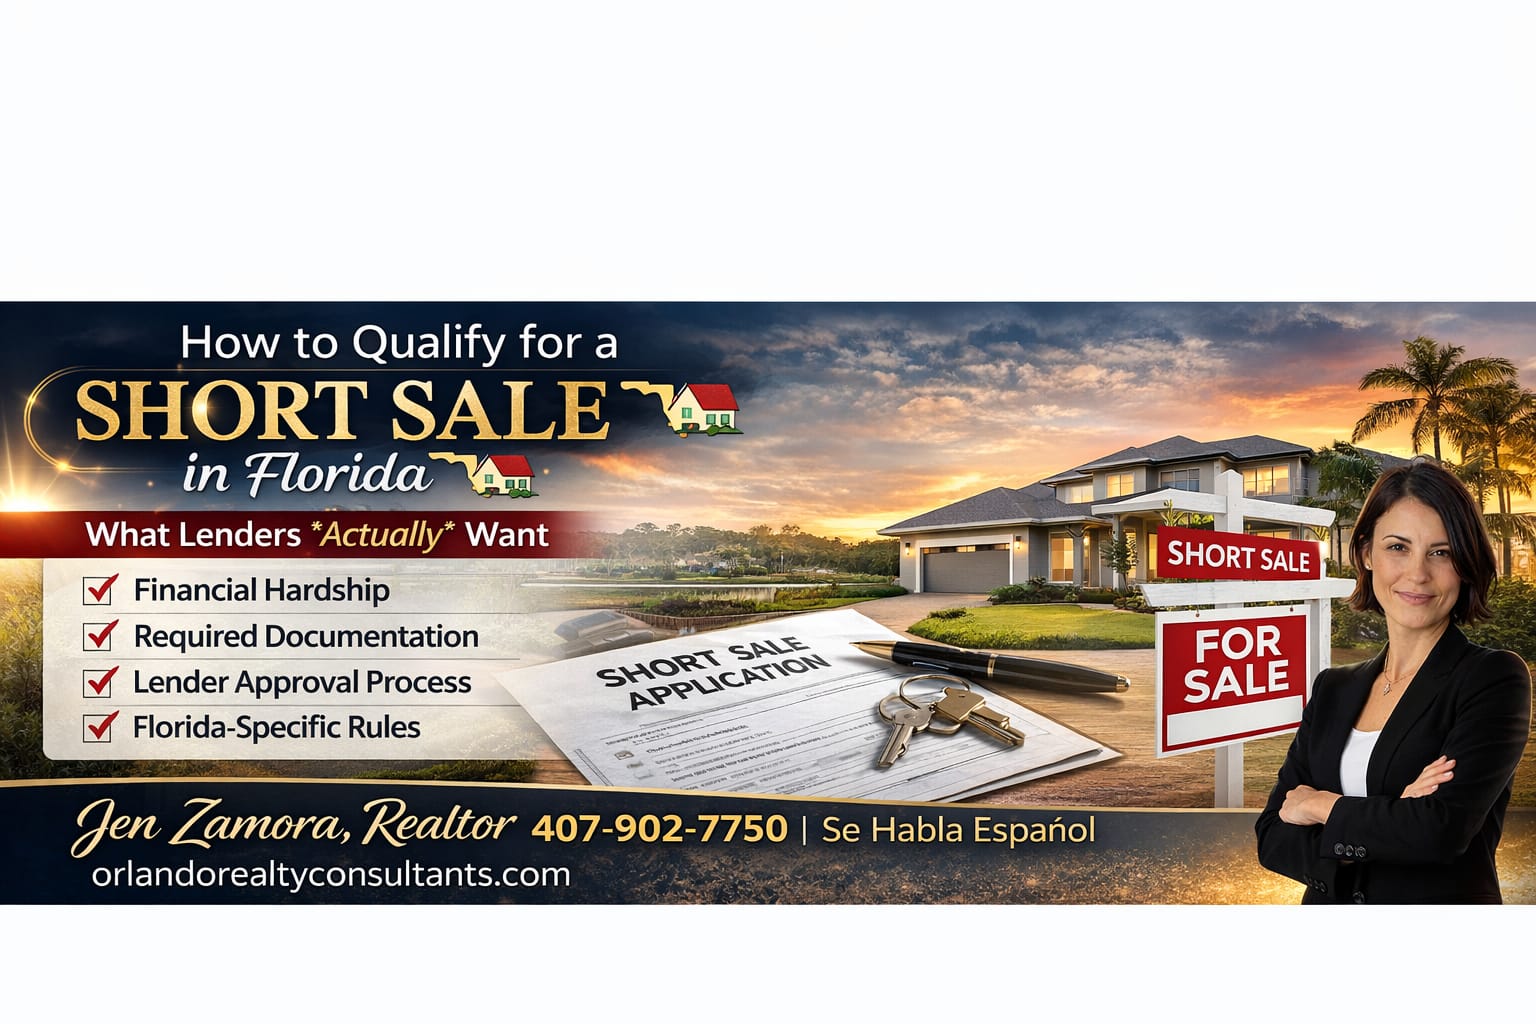
Para calificar para un short sale en Florida, debes demostrarle a tu prestamista que estás atravesando una dificultad económica legítima, que el valor actual de tu propiedad es inferior al saldo pendiente de tu hipoteca y que has presentado un expediente completo con documentación financiera, pruebas de tu situación económica y una oferta razonable de un comprador. La aprobación del prestamista es obligatoria para completar un short sale.

¿Qué es un Short Sale?

Un short sale ocurre cuando vendes tu propiedad por una cantidad inferior a lo que debes en tu hipoteca y tu prestamista acepta recibir el dinero de la venta para saldar la deuda hipotecaria, según los términos del acuerdo aprobado. Es una alternativa al foreclosure que se negocia directamente con el prestamista. Este proceso puede ayudarte a evitar algunas de las consecuencias financieras de perder tu vivienda mediante un foreclosure, reducir el impacto a largo plazo en tu historial crediticio y encontrar una solución cuando ya no puedes continuar realizando los pagos de tu hipoteca.

¿Qué Buscan los Prestamistas para Aprobar un Short Sale?

1. Dificultad Económica Comprobable

Lenders won’t approve a short sale unless you can show a true hardship — something beyond normal financial strain. Typical qualifying reasons include job loss, income reduction, divorce, medical bills, relocation, military service, or other unexpected financial burdens. You’ll need a detailed hardship letter explaining your circumstances and supporting documents (tax returns, pay stubs, bank statements).

2. Valor de la Propiedad Inferior a la Deuda Hipotecaria

Para calificar para un short sale, generalmente debes tener una deuda hipotecaria superior al valor actual de mercado de tu propiedad. Esta situación se conoce como negative equity o patrimonio neto negativo. Por ejemplo, si debes $350,000 en tu hipoteca, pero tu propiedad actualmente tiene un valor de mercado de $300,000, existe una diferencia de $50,000 entre lo que debes y lo que vale la vivienda. Para determinar el valor de la propiedad, el prestamista puede solicitar: - Una tasación profesional (appraisal). - Una opinión de precio de un corredor inmobiliario BPO - Un análisis comparativo de mercado (CMA) preparado por tu agente de bienes raíces. - Información sobre ventas recientes de propiedades similares en tu área. Si el prestamista determina que tu propiedad puede venderse por una cantidad suficiente para cubrir la deuda hipotecaria y los costos correspondientes, podría rechazar la solicitud de short sale.

3. Documentación Financiera Completa

Los documentos que generalmente solicitan los prestamistas incluyen:

  • Carta de dificultad económica (Hardship Letter): Explica las circunstancias que dificultan continuar realizando los pagos hipotecarios.
  • Declaraciones de impuestos de los últimos dos años: Permiten verificar tu historial de ingresos.
  • Comprobantes de ingresos recientes: Incluyen talonarios de pago, documentación de trabajo independiente u otras fuentes de ingresos.
  • Estados de cuenta bancarios recientes: Ayudan al prestamista a evaluar tu situación financiera actual.
  • Presupuesto mensual de ingresos y gastos: Detalla tus obligaciones económicas y gastos habituales.

Estos documentos permiten al prestamista evaluar tu capacidad económica y determinar si realmente necesitas vender tu propiedad mediante un short sale.

4. Un Comprador Calificado y una Oferta de Compra Razonable

Para obtener la aprobación final de un short sale, generalmente necesitas presentar una oferta de compra de un comprador calificado. El prestamista evaluará si la oferta refleja el valor actual de mercado de la propiedad y si el comprador tiene la capacidad financiera para completar la transacción.Una oferta sólida debe incluir: - Un contrato de compraventa debidamente firmado. - Un precio de compra razonable respaldado por ventas comparables. - Una carta de preaprobación hipotecaria, si el comprador necesita financiamiento. - Prueba de fondos disponibles, si la compra se realizará en efectivo. - Condiciones y plazos de cierre realistas. El objetivo del prestamista es recuperar la mayor cantidad posible de la deuda pendiente y asegurarse de que la venta pueda completarse satisfactoriamente. Por eso, trabajar con un agente inmobiliario con experiencia en short sales en Orlando puede ayudarte a establecer un precio competitivo, presentar una oferta bien documentada y reducir problemas durante la negociación.

5. Cooperación y Comunicación Constante con el Prestamista

Un short sale requiere paciencia, organización y comunicación continua entre el propietario, el prestamista, el comprador y los profesionales involucrados en la transacción. Durante el proceso, es importante: - Responder rápidamente a las solicitudes del prestamista. - Proporcionar documentos adicionales cuando sean necesarios. - Mantener actualizada toda la información financiera. - Cumplir con los plazos establecidos para entregar documentación. - Mantener comunicación constante con tu agente inmobiliario. - Estar preparado para un proceso de revisión que puede durar varios meses. Los prestamistas pueden solicitar documentos actualizados en diferentes etapas del proceso, incluso cuando ya se haya presentado un expediente completo. La clave para aumentar tus posibilidades de aprobación es presentar información precisa, mantener una comunicación constante y trabajar con profesionales que conozcan el proceso de short sale en Florida.

Consideraciones Específicas para Orlando y Florida

Los procesos de short sale en Florida Central tienen características particulares que deben tomarse en cuenta. El mercado inmobiliario de Orlando es dinámico, por lo que establecer un precio competitivo y trabajar con profesionales experimentados ayuda a demostrarle al prestamista que existe demanda real por la propiedad al precio de venta propuesto. La temporada del año también puede influir en la rapidez con la que se reciben ofertas.

Las leyes de Florida también pueden influir en las reclamaciones por saldos pendientes (deficiency judgments). En algunos casos, los prestamistas pueden renunciar a su derecho de reclamar la diferencia entre el saldo de la hipoteca y el monto recibido mediante el short sale. Es fundamental que esta renuncia quede claramente establecida por escrito. Consulta siempre con tu agente de bienes raíces o un abogado especializado para conocer tus derechos y obligaciones.

Lista de Verificación Paso a Paso para un Short Sale

PasoQué Debes Hacer
1Comunícate con tu prestamista para conocer los requisitos para calificar para un short sale.
2Redacta una carta explicando tu situación económica y reúne documentos que respalden tus dificultades financieras.
3Prepara tus documentos financieros, incluyendo declaraciones de impuestos, comprobantes de ingresos y activos.
4Solicita una tasación o una evaluación de precio realizada por un agente inmobiliario (BPO).
5Pon tu propiedad a la venta y encuentra un comprador calificado.
6Presenta el paquete completo de short sale al prestamista para su evaluación.
7Negocia las contraofertas y condiciones solicitadas por el prestamista.
8Completa el cierre de la venta una vez que el prestamista haya aprobado el short sale por escrito.

Ventajas y Desventajas de un Short Sale Frente a un Foreclosure

  • Ventajas - Permite evitar un foreclosure y sus posibles consecuencias. - Puede tener un impacto menos perjudicial en tu historial crediticio, dependiendo de las circunstancias. - Te permite mantener mayor control sobre el proceso de venta de tu propiedad.
  • Contras El proceso de aprobación puede tardar varios meses. No existe garantía de que el prestamista apruebe el short sale. Requiere documentación financiera detallada y coordinación constante con el prestamista.

Errores Comunes que Debes Evitar Durante un Short Sale

  • Presentar documentación financiera incompleta: Puede retrasar la evaluación de tu solicitud o provocar que el prestamista solicite información adicional.
  • Establecer un precio superior al valor de mercado: Un precio poco competitivo puede dificultar la venta y generar desacuerdos con el prestamista.
  • Aceptar ofertas de compradores sin financiamiento sólido: Esto aumenta el riesgo de que la transacción no llegue al cierre.
  • No responder rápidamente a las solicitudes del prestamista: Los retrasos en la entrega de documentos pueden afectar el proceso de aprobación.

Preguntas frecuentes sobre los requisitos para calificar para un short sale

1. ¿Tengo que estar atrasado en los pagos de mi hipoteca para calificar?

No siempre. Sin embargo, muchos prestamistas prefieren que el propietario esté atrasado en sus pagos o que exista un riesgo inminente de incumplimiento antes de considerar un short sale. Los requisitos varían según el prestamista.

2. ¿Puedo hacer un short sale si todavía no debo más de lo que vale mi casa?

Es poco común. Por lo general, los prestamistas requieren que el saldo de la hipoteca sea mayor que el valor actual de la propiedad. Sin embargo, podrían considerar ciertas excepciones cuando el propietario enfrenta dificultades económicas graves.

3. ¿Cuánto tiempo tarda el prestamista en aprobar un short sale?

El proceso generalmente puede tomar entre 3 y 6 meses, aunque el tiempo varía según el prestamista, la rapidez con la que responda y si toda la documentación requerida está completa.

4. ¿Todavía podría deber dinero después de completar un short sale?

Sí, es posible. Si el prestamista no acepta perdonar el saldo pendiente de la hipoteca, podrías seguir siendo responsable de esa deuda. Por eso, es fundamental obtener por escrito cualquier acuerdo de condonación del saldo restante.

5. ¿Puedo comprar otra casa después de un short sale?

Sí. Sin embargo, dependiendo del tipo de préstamo hipotecario que solicites, ya sea convencional o respaldado por el gobierno, podrían existir períodos de espera. Tu historial de crédito y recuperación financiera también influirán en tu capacidad para obtener una nueva hipoteca.

6. ¿Necesito contratar a un abogado para realizar un short sale?

No es obligatorio en todos los casos, pero contar con un abogado puede ser beneficioso, especialmente para revisar los acuerdos relacionados con el saldo pendiente de la hipoteca y asegurarte de comprender tus derechos y responsabilidades legales.

5. ¿Un short sale afecta mi crédito?

Sí. Un short sale puede afectar negativamente tu puntaje de crédito, aunque en algunas circunstancias el impacto puede ser menor que el de un foreclosure. El efecto dependerá de tu historial crediticio, los pagos atrasados y otros factores financieros.

8. ¿Puedo realizar un short sale por mi cuenta?

Es posible, pero el proceso puede ser complicado. Muchos prestamistas prefieren trabajar con profesionales de bienes raíces y requieren que la propiedad se anuncie en el MLS. Contar con un agente experimentado en short sales puede ayudarte a preparar la documentación, negociar con el prestamista y encontrar compradores calificados.

Próximos pasos

Si estás considerando realizar un short sale o deseas explorar otras alternativas que puedan ayudarte a proteger tu futuro financiero, comunícate con un Realtor experimentado y un equipo que comprenda cómo preparar y presentar tu caso para aumentar las posibilidades de obtener la aprobación del prestamista.

Llamar En Orlando Realty Consultants, combinamos más de dos décadas de experiencia en bienes raíces en Central Florida con investigaciones específicas de cada vecindario para ayudar a los propietarios a tomar decisiones con confianza. at 407-902-7750 para conocer tus opciones y recibir orientación personalizada. ¡Se habla español!

Cuando estés listo, te ayudaremos a desarrollar una estrategia de venta adecuada y a conectar tu propiedad con compradores potenciales para mejorar tus posibilidades de completar exitosamente el short sale. No somos simplemente agentes de bienes raíces somos profesionales comprometidos en ayudarte a encontrar soluciones y tomar decisiones informadas en el mercado inmobiliario de Florida Central. ¿Buscas agentes de bienes raíces con experiencia en Orlando que puedan ayudarte durante todo el proceso?
¡Mantengámonos en contacto!

Nuevo cliente potencial de formulario ORC

"*" indica los campos obligatorios

Este campo es para fines de validación y debe dejarse sin cambios.
Trastorno obsesivo-compulsivo*

Bienes raíces de lujo en Florida en 2026: ¡Lo que buscan los compradores!

Luxury real estate in FL refers to high-end properties typically priced in the top 5–10% of a market’s pricing range, offering premium amenities, elite locations, and sophisticated design. In 2026, buyers seek privacy, technological integration, and lifestyle appeal — especially in Central Florida markets like Windermere and Isleworth.

What Is Luxury Real Estate in FL?

Luxury real estate in Florida encompasses high-value homes — from waterfront estates and golf course mansions to designer condos with panoramic views. These properties aren’t just expensive; they offer features, craftsmanship, and exclusivity beyond standard homes, often priced well above the local median. In metro areas like South Florida, ultra-luxury homes above $10M have hit historic levels of sales activity. :contentReference[oaicite:0]{index=0}

Why Florida Still Dominates the Luxury Market

  • No state income tax: Wealth migration from high-tax states continues to fuel demand.
  • Coastal and lakefront access: Premium water views remain a perennial draw.
  • Strong international interest: Buyers from Latin America, Europe & Asia still invest here. :contentReference[oaicite:1]{index=1}
  • Stable appreciation: Luxury prices are rising faster than many other U.S. markets. :contentReference[oaicite:2]{index=2}

Key Trends Shaping Luxury Real Estate in FL for 2026

1. Balanced Market With Smart Buyer Advantage

After the pandemic surge, Florida’s luxury market has matured. Inventory is up in some segments, giving buyers more options, while ultra-prime properties remain competitive. :contentReference[oaicite:3]{index=3}

2. Tech, Security & Sustainability

Smart home systems, advanced security, and eco-friendly design are now expected features in high-end homes. These upgrades increase comfort and long-term value. :contentReference[oaicite:4]{index=4}

3. Shift Toward Turnkey & Lifestyle Luxury

Buyers increasingly prefer move-in ready estates with curated finishes, wellness spaces, and functional luxury over shell homes that need renovation. :contentReference[oaicite:5]{index=5}

4. Diverse Buyer Profiles

Luxury buyers range from families looking for spacious estates with privacy to professionals wanting modern amenities and investors seeking resilient assets. International and out-of-state buyers remain important demand drivers. :contentReference[oaicite:6]{index=6}

What Buyers Expect in Luxury Homes

  • Direct waterfront or panoramic views
  • High-end kitchen and baths with designer fixtures
  • In-home wellness and fitness areas
  • Dedicated office space with premium connectivity
  • Custom finishes and high-end materials

Luxury Real Estate in Orlando: Local Market Highlights

Central Florida is carving out its own luxury identity. Communities like Windermere, Isleworth, and Lake Nona are prized for lakefront living, strategic locations near top schools, and proximity to lifestyle hubs. Prices in luxury segments here are strong, often exceeding the regional median by a significant margin. :contentReference[oaicite:7]{index=7}

Why Central Florida Stands Out

  • Lakefront & gated neighborhoods: High demand for privacy and prestige.
  • Proximity to Orlando amenities: Easy access to airports, schools, entertainment, and dining.
  • Secondary home appeal: Many buyers use these estates as retreats or investment properties.

How to Navigate Buying Luxury Real Estate in FL

  1. Define your priorities: Waterfront vs. golf vs. privacy.
  2. Get pre-qualified for financing: Luxury buyers benefit from cash positioning or jumbo loans.
  3. Work with an experienced local agent: Expertise matters for negotiating terms and uncovering off-market opportunities.
  4. Inspect with experts: High-end features often need specialized inspection (smart systems, pools, docks).
  5. Understand closing costs: Budget for fees — see CFPB – Closing Cost Guide for details.

Errores comunes que cometen los compradores

  • Underestimating ongoing maintenance costs
  • Skipping detailed inspections due to confidence in luxury finishes
  • Failing to consider insurance costs (especially coastal properties)

Luxury Real Estate & Local Infrastructure

Investing in the region means understanding community dynamics. The Ciudad de Orlando continues to expand infrastructure and quality-of-life amenities, making nearby luxury properties more attractive to long-term residents and investors alike.

Quick Comparison: Luxury Market Stats

SegmentTrendOrlando Focus
Ultra-Luxury ($10M+)High demand, cash salesLess common than South FL but rising interest
Lakefront EstatesStrong buyer appetiteWindermere & Butler Chain
Modern Luxury HomesSmart systems + sustainabilityUrban + suburban appeal

Resumen: ¿Cuánto tiempo debes esperar para completar un Short Sale

Luxury real estate in FL remains resilient, appealing to diverse buyers seeking lifestyle, location, and long-term value. Central Florida — especially Orlando’s premier communities — continues to attract attention for both primary residences and investment properties. With shifting preferences and evolving trends, working with an expert Realtor makes all the difference.

Ready to Explore Luxury Homes in Florida?

If you’re serious about buying or selling a luxury property, let Orlando Realty Consultants guide you through every step. Se habla español — call us at 407-902-7750 for tailored insights and elite service.

Explore options like Luxury Homes in FLorida and get started today.

Preguntas Frecuentes

¿Qué define a los bienes raíces de lujo en Florida?

Los bienes raíces de lujo en FL por lo general se refieren a propiedades en el nivel de precios más alto de su mercado, que ofrecen ubicaciones prémium y comodidades que van más allá de las viviendas estándar.

¿Se considera a Orlando un mercado de lujo?

Sí: los vecindarios de alta gama, las propiedades frente al lago y las comunidades exclusivas y privadas de Orlando continúan exigiendo precios elevados y un fuerte interés por parte de los compradores.

¿Cuánto debo presupuestar para los costos de cierre de una casa de lujo?

Closing costs vary based on price and financing. For guidance, check the CFPB – Closing Cost Guide.

Are international buyers active in FL luxury real estate?

Yes, buyers from around the world continue investing in Florida luxury properties for lifestyle and tax advantages.

What trends should luxury buyers watch in 2026?

Expect more tech-integrated homes, turnkey properties, and amenities that support wellness and remote work.

How do property taxes affect luxury homes in FL?

Property taxes are based on assessed value. For luxury homes, taxes can be substantial — work with a local agent to understand liabilities.

Should I finance or pay cash for a luxury home?

Cash gives negotiation leverage, but many buyers use jumbo financing. Your strategy should align with financial goals.

Which areas of Florida are hottest for luxury real estate?

South FL (Miami, Palm Beach) leads in ultra-luxury; Central Florida’s elite communities are also gaining steam.

¡Mantengámonos en contacto!

Nuevo cliente potencial de formulario ORC

"*" indica los campos obligatorios

Este campo es para fines de validación y debe dejarse sin cambios.
Trastorno obsesivo-compulsivo*

Investor’s Guide to Profiting from Short Sales in 2025

Short sales have always been a bit of a mystery to many investors, often misunderstood or overlooked in favor of flashier investment strategies. But let me tell you — 2025 is shaping up to be a banner year for those savvy enough to navigate the Orlando short sale market. As a seasoned short sale Realtor in Orlando, FL, I’ve seen the tides rise and fall, and right now, we’re standing at the edge of a golden opportunity.

In this blog post, I’m going to pull back the curtain and walk you through how you, as an investor, can profit from short sales in 2025. We’ll break down what’s different this year, what strategies are working best, and how to position yourself as a winning buyer in this unique corner of real estate.


What is a Short Sale and Why Should Investors Care in 2025?

A short sale occurs when a homeowner sells their property for less than what’s owed on the mortgage, and the lender agrees to accept the reduced amount to avoid foreclosure. While these sales can be time-consuming and complex, the potential for buying real estate at below-market prices is unmatched.

So, why 2025? After a rollercoaster ride through inflation, rising interest rates, and economic slowdowns, many homeowners are finding themselves underwater on their mortgages. Distress is rising — and with it, the volume of potential short sales. For investors, that means inventory, discounts, and opportunity.


Why Short Sales Make Sense for Investors Right Now

Unlike auctions or foreclosures, short sales allow investors to:

  • Do inspections before closing — a huge plus.
  • Negotiate with motivated sellers — often leading to better terms.
  • Avoid eviction headaches, as the seller is willingly participating in the sale.
  • Pick up properties at 10-30% below market value — if you know what to look for.

And right now, banks are more flexible than ever. They’d rather recoup part of their investment than take a total loss. That puts power into the hands of well-prepared investors.


How the 2025 Market is Favoring Short Sales

We’re in a market where Las tasas actuales remain higher than they were pre-2020, and many homeowners who bought at the peak of the market are now seeing their property values dip. Combine that with job layoffs in tech, a pullback in the gig economy, and ballooning credit debt, and you’ve got a recipe for financial strain.

In 2025, we’re already seeing:

  • An increase in distressed properties in suburban and exurban areas.
  • Banks actively streamlining short sale processes to move properties off their books faster.
  • Investors with cash or flexible financing being prioritized.

For the savvy, this isn’t just a trend — it’s a signal to act.


How to Identify a Profitable Short Sale Opportunity

Not all short sales are created equal. Here’s how I coach my investor clients to vet a potential deal:

1. Know the ARV (After Repair Value)

Before even thinking about an offer, calculate the realistic resale price. You want at least a 20-30% margin between your purchase price (plus repairs) and the expected resale value. Use comps, not guesswork.

2. Understand the Lien Situation

Many short sales involve multiple liens. If there are second mortgages, HOA dues, or tax liens, those need to be addressed. I always run a preliminary title search to assess the headache level.

3. Gauge the Lender’s Willingness

Some banks are easier to work with than others. As an experienced short sale agent, I’ve built relationships with banks and negotiators that can cut timelines in half — a critical edge.

4. Evaluate Repair Costs Realistically

A beautiful deal on paper can fall apart with unseen foundation issues or a roof that needs replacement. Always get a professional inspection, even if the home looks solid.


Winning Strategies for Investors in Short Sales

Let’s talk tactics — here’s how successful investors are making short sales work in 2025:

1. Cash is King (But Financing Can Work Too)

Cash deals close faster and are preferred by banks, but if you’re financing, work with lenders who understand short sales and can issue pre-approval letters quickly.

2. Speed Up the Process with a Pro Realtor

Don’t go it alone. Short sales are full of paperwork, negotiation, and follow-ups. A good short sale Realtor will handle all communication with the lender, package the deal to get approved, and keep things moving.

3. Build a Short Sale Funnel

The pros don’t chase one deal at a time. I help my investors line up 3-5 short sale properties in various stages. When one falls through (and sometimes they do), they’re already halfway through another.

4. Offer Help to the Homeowner

Want to close more deals? Make the process easier for the distressed homeowner. Help them with moving costs, offer flexible timelines, and keep the lines of communication open. A little empathy can go a long way toward closing.


Mistakes Investors Must Avoid in Short Sales

Even experienced investors slip up. Here are the top mistakes I see:

  • Underestimating the timeline. Short sales are not quick flips. Expect 60–120 days, minimum.
  • Not understanding lender requirements. Each bank has its own process. You need someone who speaks their language.
  • Falling in love with one deal. Don’t get emotionally invested. If it’s too complex or dragging on, walk away.
  • Skipping the inspection. Hidden issues can turn a deal into a money pit.

Final Thoughts — The Time to Act is Now

Short sales aren’t sexy. They don’t come with auctions or hype. But in 2025, they’re a quiet goldmine for investors who know how to play the game. I’ve helped dozens of investors close short sales that have turned into profitable rentals, fix-and-flips, and even long-term appreciation plays.

If you’re ready to take advantage of the 2025 market shift, it’s time to partner with a Realtor who lives and breathes short sales. These deals take patience, skill, and experience — but the returns? Absolutely worth it.

Whether you’re new to real estate or looking to scale your investment portfolio, short sales can be your next big win. Let’s find those hidden gems together.

¡Mantengámonos en contacto!

Nuevo cliente potencial de formulario ORC

"*" indica los campos obligatorios

Este campo es para fines de validación y debe dejarse sin cambios.
Trastorno obsesivo-compulsivo*

Waterfront Living in Florida: Is It Worth the Extra Cost?

Imagine waking up to the sound of gentle waves lapping against the shore, enjoying breathtaking sunset views from your backyard, and having direct access to Florida’s stunning waterways. 🌇 Waterfront living sounds like a dream—but is it worth the extra cost? As an experto en bienes raíces en Orlando,, I’m here to break down the pros, cons, and key factors you should consider before making the investment. 💼🏡

The Allure of Waterfront Living in Florida 💟

There’s a reason why waterfront properties in Florida are among the most sought-after real estate investments. Whether it’s a home by the ocean, a lakefront retreat, or a canal-side villa, these properties offer unmatched beauty and a lifestyle many aspire to. But along with the stunning views and exclusivity, waterfront homes come with a higher price tag. Here’s why:

1. Unparalleled Views & Serenity 🌆

Waterfront homes provide breathtaking scenery that you can’t get anywhere else. The tranquility of watching the sunrise over the ocean or the peaceful ripples of a lake create a serene environment that can significantly improve your quality of life. 🌿

2. Higher Property Value & Investment Potential 💼

Waterfront properties generally appreciate faster than landlocked homes due to their limited supply and high demand. If you’re looking for a solid real estate investment, buying a waterfront home could pay off in the long run. 🏠📈

3. Direct Water Access & Outdoor Activities 🎣

Love fishing, boating, or kayaking? ⛵️ Many Florida waterfront homes provide direct access to water, allowing you to enjoy these activities right from your backyard. No need for long drives to the marina—you’re already there!

4. Health & Well-Being Benefits 💪

Living near water has been linked to reduced stress, improved mental health, and an overall happier lifestyle. The calming effects of water, fresh air, and natural surroundings can boost your well-being. 🏡🧠


The Hidden Costs of Waterfront Living ⚡

While the perks of waterfront living are undeniable, it’s crucial to be aware of the potential downsides and hidden costs before making your decision. 📍 Here are some key factors to consider:

1. Higher Purchase Price & Property Taxes 💸

Waterfront homes often come with premium price tags. On top of that, property taxes can be significantly higher due to their increased value. Before purchasing, factor in these additional costs to ensure it fits within your budget. 📃

2. Homeowners Insurance & Flood Risk 🌊

Living near water comes with an increased risk of flooding and hurricane damage. Florida homeowners insurance can be costly, and you may need additional flood insurance, which can add thousands to your annual expenses. Check FEMA flood zone maps and insurance quotes before buying. 📢

3. Maintenance & Wear-and-Tear 🪑

Waterfront homes require more upkeep due to exposure to salt air, humidity, and storms. Corrosion, mold, and water damage are common issues that can lead to costly repairs. Regular maintenance, including seawall inspections and dock repairs, is essential. 🛠

4. HOA & Special Assessments 💼

Many waterfront communities have homeowner association (HOA) fees to maintain shared amenities like private docks and seawalls. Some areas also impose special assessments for coastal protection projects, so be sure to research potential extra costs. 📊


Best Florida Locations for Waterfront Living 🌎

If you’re considering waterfront living in Florida, location matters! Here are some of the top areas known for their stunning waterfront properties:

1. Miami & Fort Lauderdale 🌴

  • Luxury oceanfront condos & high-end estates
  • Bustling nightlife & cultural scene
  • Higher price tags but strong investment potential

2. Naples & Marco Island 🏖

  • Quiet, upscale coastal communities
  • Beautiful beaches & golf courses
  • Higher insurance costs but excellent quality of life

3. Tampa Bay & St. Petersburg 🌊

  • Affordable compared to Miami
  • Booming job market & great schools
  • Mix of waterfront homes on the bay & Gulf of Mexico

4. Orlando & Central Florida Lakes 🌟

  • Ideal for lakefront living, with options like Lake Butler & Lake Nona
  • Less hurricane risk than coastal properties
  • Great for boating, fishing & water sports

Is It Worth It? The Final Verdict 🧐

Waterfront living in Florida is a dream come true for many—but it’s essential to weigh the pros and cons before taking the plunge. If you love nature, water activities, and exclusivity, and you’re prepared for the extra costs and maintenance, then a waterfront home may be the perfect investment. However, if budget constraints, insurance expenses, and upkeep are a concern, you may want to consider a lakefront or canal-front home with lower risks. 💡

Pro Tip: Work with a Local Real Estate Expert! 🏢

Every waterfront property is unique, and the market can be competitive. Working with an experienced agente inmobiliario en Orlando can help you navigate the options, assess risks, and find a property that meets your lifestyle and financial goals. 🚀

Thinking about making the move? Let’s find your dream waterfront home in Florida! 💎 Drop a comment below or reach out to start your home search today. 407-902-7750

¡Mantengámonos en contacto!

Nuevo cliente potencial de formulario ORC

"*" indica los campos obligatorios

Este campo es para fines de validación y debe dejarse sin cambios.
Trastorno obsesivo-compulsivo*

Step-by-Step Short Sale Process for Homeowners

Navigating the short sale process as a homeowner can feel like trying to find your way through a financial maze. As a short sale Realtor, I’ve worked with dozens of homeowners who were confused, overwhelmed, and unsure of what steps to take. That’s why I’ve broken down the entire short sale journey into an easy-to-follow, step-by-step guide. Whether you’re trying to avoid foreclosure or simply need a financial reset, this post will walk you through everything you need to know, with insight straight from the field.


What Is a Short Sale? (And Why Homeowners Choose It)

Before we dive into the step-by-step process, let’s make sure we’re on the same page. A short sale happens when a homeowner sells their property for less than the balance remaining on the mortgage. The lender agrees to accept less than what is owed to avoid the more costly and time-consuming foreclosure process.

Homeowners typically pursue short sales when they:

  • Are behind on mortgage payments
  • Owe more than the home is worth (underwater mortgage)
  • Are experiencing a financial hardship like job loss, divorce, or medical bills

It’s not the easiest path, but with the right Realtor (like yours truly), it can be the smartest.


Step 1: Understand Your Financial Situation and Options

As a Realtor in Orlando, FL , my first goal is to sit down with you and get the full picture of your financial health. This is a critical step and often the most emotional one. You’ll need to gather:

  • Mortgage statements
  • Bank account summaries
  • Planillas de contribución sobre ingresos (Tax Returns): Ayudan a verificar los ingresos y la información financiera del propietario.
  • Pay stubs (or unemployment documentation)

At this point, I’ll also discuss alternative options like loan modifications or deed-in-lieu of foreclosure. If the short sale is the best route, we move forward with confidence.


Step 2: Hire a Short Sale-Savvy Realtor (That’s Me!)

Not all Realtors are created equal when it comes to short sales. It’s a complex process involving multiple parties—your lender, buyers, appraisers, negotiators, and possibly even attorneys. You need someone who:

  • Has a proven track record with short sales
  • Knows how to handle lender negotiations
  • Understands market dynamics and pricing strategies

Once hired, I’ll handle the listing, the paperwork, the buyer vetting, and most importantly, the communication with your lender.


Step 3: Submit the Short Sale Package to Your Lender

This is one of the most important (and paperwork-heavy) steps in the process. A short sale package typically includes:

  • A hardship letter explaining your situation
  • Financial statements
  • Two years of tax returns
  • Estados de cuenta
  • A listing agreement with your Realtor
  • A purchase offer from a qualified buyer

The goal here is to convince your lender that you’re truly in financial distress and that accepting a short sale is their best bet. Pro tip: honesty and transparency go a long way here. Don’t sugarcoat your hardship—be real.


Step 4: Price the Home Competitively (Not Too High, Not Too Low)

Pricing a short-sale home is both an art and a science. Too high, and it won’t sell—too low, and the lender may reject the offer. Here’s what I do to get it right:

  • Pull recent comparable sales in the area
  • Factor in market trends and property condition
  • Consider how motivated the bank is to sell

Sometimes the bank will order a Broker Price Opinion (BPO) to determine the home’s value. This is where my market knowledge really comes in handy—I know how to make a compelling case for a price that’s both fair and bank-acceptable.


Step 5: List, Market, and Secure a Buyer

Once we’ve agreed on a price and listed the home, it’s go time. As your Realtor, I’ll go full-throttle on marketing:

  • High-quality listing photos and videos
  • Compelling property descriptions
  • MLS exposure and social media promotion
  • Targeted outreach to investors and homebuyers

When offers come in, I’ll vet them carefully. Not every buyer is equipped to handle a short sale. I make sure they’re pre-approved (or have proof of funds), patient, and ready for a potentially lengthy process.


Great! Let’s continue with the next steps in the short sale process for homeowners.


Step 6: Submit the Buyer’s Offer to the Lender

Once we’ve got a serious buyer on board, it’s time to submit their offer along with the complete short sale package to your lender. This includes:

  • The buyer’s signed purchase agreement
  • Their pre-approval letter or proof of funds
  • Any lender-specific short sale documents
  • A HUD-1 or preliminary net sheet showing estimated costs and proceeds

From here, the waiting game begins. Some lenders respond within weeks, while others can take several months. As your Realtor, I stay on top of the lender with regular follow-ups, ensuring your file doesn’t get lost in a pile.

Step 7: Navigate the Lender’s Review Process

This is the part where patience is key. The lender will review the offer and all documentation to determine if the short sale is in their best interest. They’ll consider:

  • The net proceeds from the sale versus foreclosure
  • The buyer’s offer in relation to market value
  • Your financial hardship and documentation

They might order another Broker Price Opinion or appraisal. Sometimes they’ll counter the buyer’s offer or ask for additional documents. I’ll negotiate directly with them and communicate any updates to you and the buyer.

Here’s a little insider tip: if your lender sees that everything is complete, well-organized, and backed by a professional Realtor, they’re more likely to respond quickly and favorably. That’s why my attention to detail here is critical.


Step 8: Receive Short Sale Approval Letter

When the lender finally gives the green light, they’ll issue an official short sale approval letter. This document outlines the terms of the sale, including:

  • Approved purchase price
  • Closing deadline
  • Any forgiven debt or deficiency
  • Terms for paying off other liens or closing costs

We review this letter carefully to make sure everything is accurate and acceptable. If you’re working with a legal or tax advisor, this is the time to loop them in.

Once you sign off, we’re almost at the finish line.


Step 9: Close the Deal

Now that we have lender approval, we move into standard closing procedures—just like in a traditional real estate sale. This includes:

  • Final inspections and walkthroughs
  • Title search and lien clearance
  • Closing disclosures and documentation
  • Coordinating with escrow and title agents

At this point, you’ll sign the necessary documents, hand over the keys, and walk away knowing that you avoided foreclosure. It may not be the outcome you originally imagined when buying the home—but it’s a huge step toward financial recovery and peace of mind.


Step 10: Rebuild and Move Forward

After closing, many homeowners feel a wave of relief—but also uncertainty. What’s next?

As your Realtor, I don’t disappear after the deal is done. I’ll offer guidance on how to:

  • Rebuild your credit (a short sale impacts your score less than foreclosure)
  • Prepare for future homeownership (typically after 2–3 years)
  • Explore renting or downsizing options
  • Understand potential tax implications (consult with a tax advisor)

This chapter may be closing, but a new one is just beginning. And the best part? You’re no longer stuck in a house that’s weighing you down.


Final Thoughts from a Short Sale Realtor

A short sale isn’t just a transaction—it’s a journey. And like any journey, it’s much easier when you have someone experienced guiding you every step of the way. I’ve helped countless homeowners move from stress and uncertainty to clarity and freedom.

Yes, short sales require time, paperwork, and persistence. But they also offer something incredibly valuable: a second chance. If you’re feeling overwhelmed by mortgage payments or fear foreclosure is looming, don’t wait. Reach out. Let’s talk about your options, no judgment, just support.

Remember: every successful short sale starts with one decision—to take action.


FAQs About the Short Sale Process

1. How long does a short sale take from start to finish?
Most short sales take between 3 to 6 months, but timelines vary depending on the lender and complexity of the situation.

2. Will a short sale ruin my credit?
While a short sale will affect your credit, it’s generally less damaging than a foreclosure. Most people can qualify for another mortgage in 2–3 years.

3. Can I do a short sale without missing mortgage payments?
Yes, although lenders are more likely to approve a short sale if you’re behind on payments or facing imminent hardship.

Experto en short sales en Orlando

4. What happens to the unpaid balance after the short sale?
It depends on your lender. Some forgive the deficiency entirely, while others may require a repayment plan or lump sum. Always review the approval letter carefully.

5. Do I need to pay taxes on forgiven debt in a short sale?
In some cases, forgiven debt can be considered taxable income. However, many homeowners qualify for exclusions under the Mortgage Forgiveness Debt Relief Act. Always consult a tax professional.


¡Mantengámonos en contacto!

Nuevo cliente potencial de formulario ORC

"*" indica los campos obligatorios

Este campo es para fines de validación y debe dejarse sin cambios.
Trastorno obsesivo-compulsivo*