Buying a home in Orlando can feel overwhelming, especially when it comes to financing. One of the most popular loan programs for first-time buyers is the FHA loan. These government-backed loans help buyers qualify with lower credit scores and smaller down payments.
Quick Answer: FHA loan Florida requirements typically include a minimum 580 credit score for a 3.5% down payment, steady income, a manageable debt-to-income ratio, and a home that meets FHA property standards. Loan limits vary by county, and buyers must pay FHA mortgage insurance. These loans are popular with first-time homebuyers in Orlando.
What Is an FHA Loan?
An FHA loan is a mortgage backed by the Federal Housing Administration. The goal is simple: make homeownership more accessible.
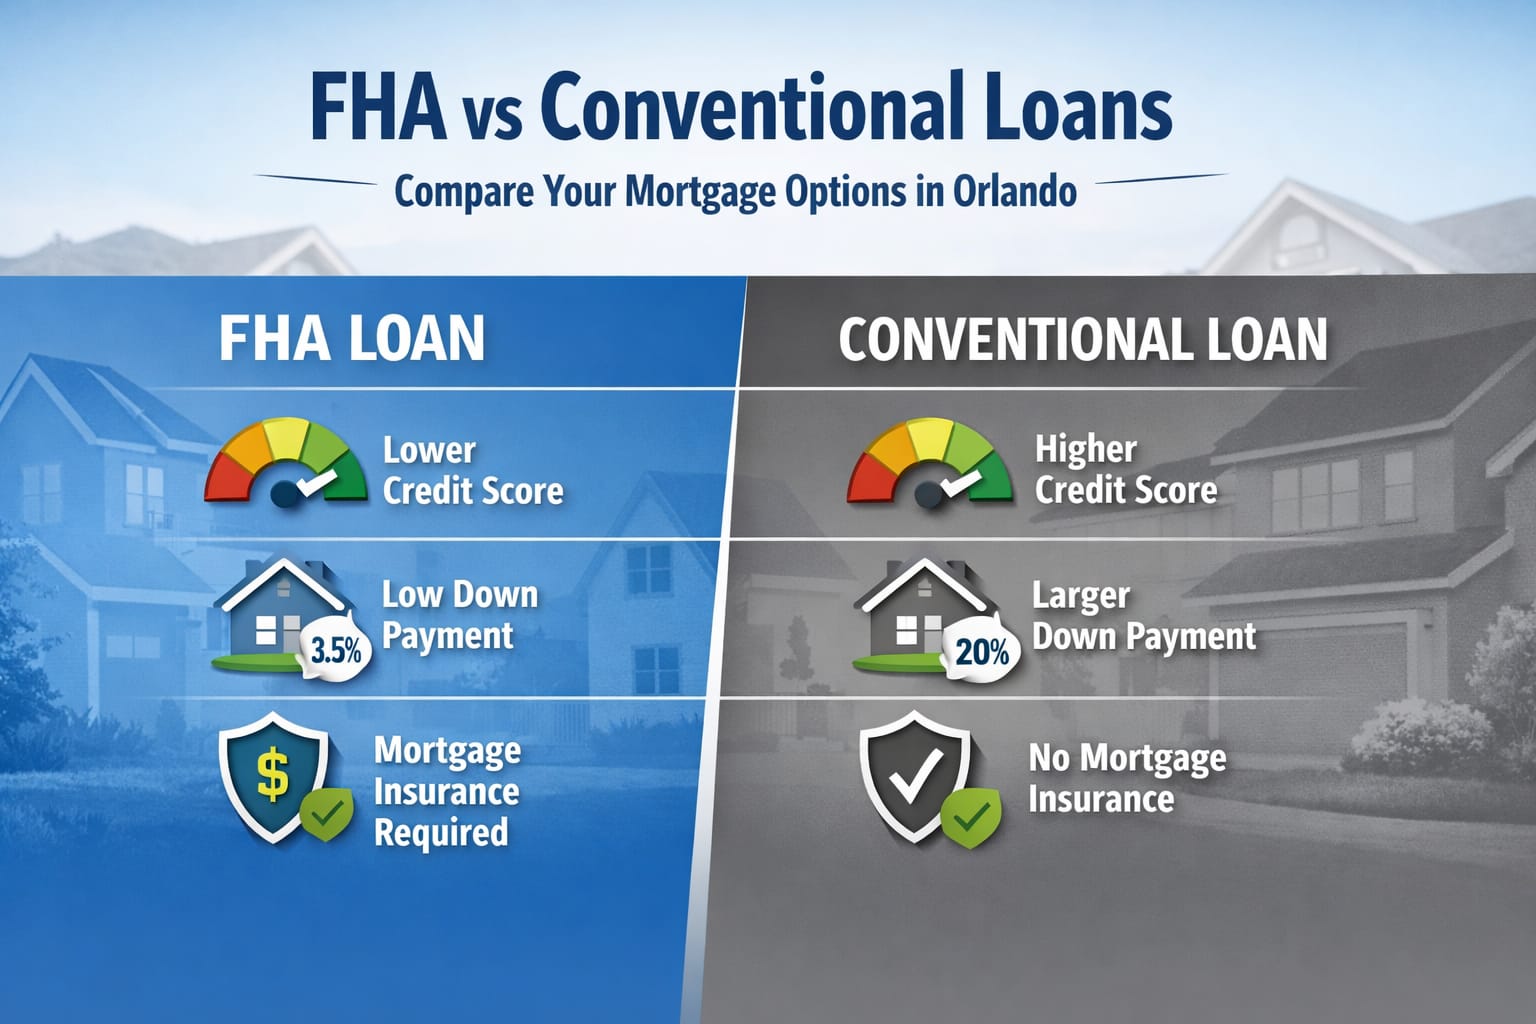
Compared with conventional loans, FHA loans allow:
- Lower credit scores
- Smaller down payments
- More flexible qualification standards
This is why FHA financing is extremely common among buyers purchasing their first home in Orlando.
If you’re planning to purchase property locally, reviewing a full Orlando home buying guide can also help you prepare.
FHA Loan Florida Requirements
To qualify for an FHA mortgage in Florida, buyers generally must meet several key requirements.
| Requirement | Typical FHA Guideline |
|---|---|
| Minimum Credit Score | 580 for 3.5% down payment |
| Down Payment | 3.5% minimum |
| Debt-to-Income Ratio | Usually under 43% |
| Employment History | 2 years stable income preferred |
| Primary Residence | Home must be owner occupied |
| Mortgage Insurance | Required for all FHA loans |
These guidelines are national FHA standards, but loan limits and some qualification details vary in Florida depending on the county.
FHA Loan Credit Score Requirements
Your credit score plays a big role in FHA approval.
- 580+ credit score → eligible for 3.5% down payment
- 500–579 score → may require 10% down
- 620+ → typically easier approval with lenders
Many buyers assume they need perfect credit to buy a home, but FHA loans are designed for buyers rebuilding credit or entering the market for the first time.
FHA Down Payment Requirements
The biggest reason buyers choose FHA financing is the low down payment.
With a 580 credit score, buyers can purchase a home with just 3.5% down.
For example:
- $300,000 home → $10,500 down payment
- $400,000 home → $14,000 down payment
In many cases, buyers can also receive help through Florida down payment assistance programs.
FHA Loan Limits in Florida
FHA loan limits change each year and vary by county.
For the Orlando area (Orange County), the FHA loan limit is typically aligned with national conforming limits.
You can confirm current limits through the HUD FHA loan limit lookup tool.
FHA Property Requirements
Not every home qualifies for FHA financing.
The property must meet FHA appraisal and safety standards, including:
- Safe structure and foundation
- Working electrical and plumbing
- No significant roof damage
- No major safety hazards
This protects buyers from purchasing homes with serious issues.
It’s also smart to watch for common problems buyers overlook. Here are the principales señales de alerta al comprar una casa.
Pros and Cons of FHA Loans
Ventajas
- Low down payment
- Lower credit score requirements
- Higher approval rates for first-time buyers
- Flexible income qualifications
Desventajas
- Mortgage insurance is required
- Loan limits may restrict price range
- Property condition rules can be strict
Common FHA Loan Mistakes Buyers Make
- Opening new credit cards before closing
- Changing jobs during loan approval
- Not budgeting for closing costs
- Assuming any home will qualify for FHA
Many buyers also forget about additional expenses. Learn about the hidden costs of buying a home in Florida.
How FHA Loans Work in Orlando
In the Orlando real estate market, FHA loans are extremely common among first-time buyers and relocating families.
Many neighborhoods in the area fall within FHA loan limits, making them attractive options for buyers who want affordable monthly payments.
However, Orlando is competitive. Homes that qualify for FHA financing often receive multiple offers.
Understanding the local market — including how interest rates affect Orlando home prices — helps buyers make smarter decisions.
Step-by-Step FHA Loan Process
- Check your credit score
- Speak with an FHA-approved lender
- Obtén una preaprobación
- Start house hunting
- Submit an offer
- FHA appraisal and underwriting
- Close on your home
Resumen: ¿Cuánto tiempo debes esperar para completar un Short Sale
FHA loan Florida requirements are designed to make homeownership more accessible. With flexible credit guidelines and a low down payment, FHA financing continues to help thousands of buyers purchase homes every year.
For Orlando buyers especially, FHA loans can be one of the fastest ways to enter the real estate market.
Work With an Orlando Real Estate Expert
If you’re considering buying a home using an FHA loan in Orlando, working with the right Realtor can make the entire process smoother.
En Orlando Realty Consultants, we help buyers navigate financing options, identify homes that qualify for FHA loans, and negotiate competitive offers.
Call or text 407-902-7750 to start your home search today.
Serving buyers across Orlando, Florida.
Se Habla Español.
Preguntas Frecuentes
What credit score is needed for an FHA loan in Florida?
Most FHA loans require a minimum credit score of 580 to qualify for the 3.5% down payment program. Some lenders may allow lower scores with a larger down payment.
How much is the FHA down payment in Florida?
The minimum down payment is 3.5% if your credit score is 580 or higher.
Are FHA loans only for first-time buyers?
No. FHA loans are popular with first-time buyers but can also be used by repeat buyers purchasing a primary residence.
Do FHA loans require mortgage insurance?
Yes. FHA loans require both upfront mortgage insurance and monthly mortgage insurance payments.
What types of homes qualify for FHA loans?
Single-family homes, some condos, and certain townhomes may qualify if they meet FHA property standards.
Can FHA loans be used for investment properties?
No. FHA loans are only available for primary residences.
What are FHA loan limits in Orlando?
Loan limits change annually. Buyers can check current limits using HUD’s FHA loan limit tool.
How long does FHA loan approval take?
Most FHA loans close within 30–45 days depending on lender processing time.
Can closing costs be included in an FHA loan?
Closing costs usually cannot be rolled into the loan but may be paid by the seller or covered by assistance programs.
Is FHA financing common in Orlando?
Yes. FHA loans are widely used by first-time buyers in the Orlando housing market.