FHA Loan Florida Requirements: Down Payment & Credit

Buying a home in Orlando can feel overwhelming, especially when it comes to financing. One of the most popular loan programs for first-time buyers is the FHA loan. These government-backed loans help buyers qualify with lower credit scores and smaller down payments.

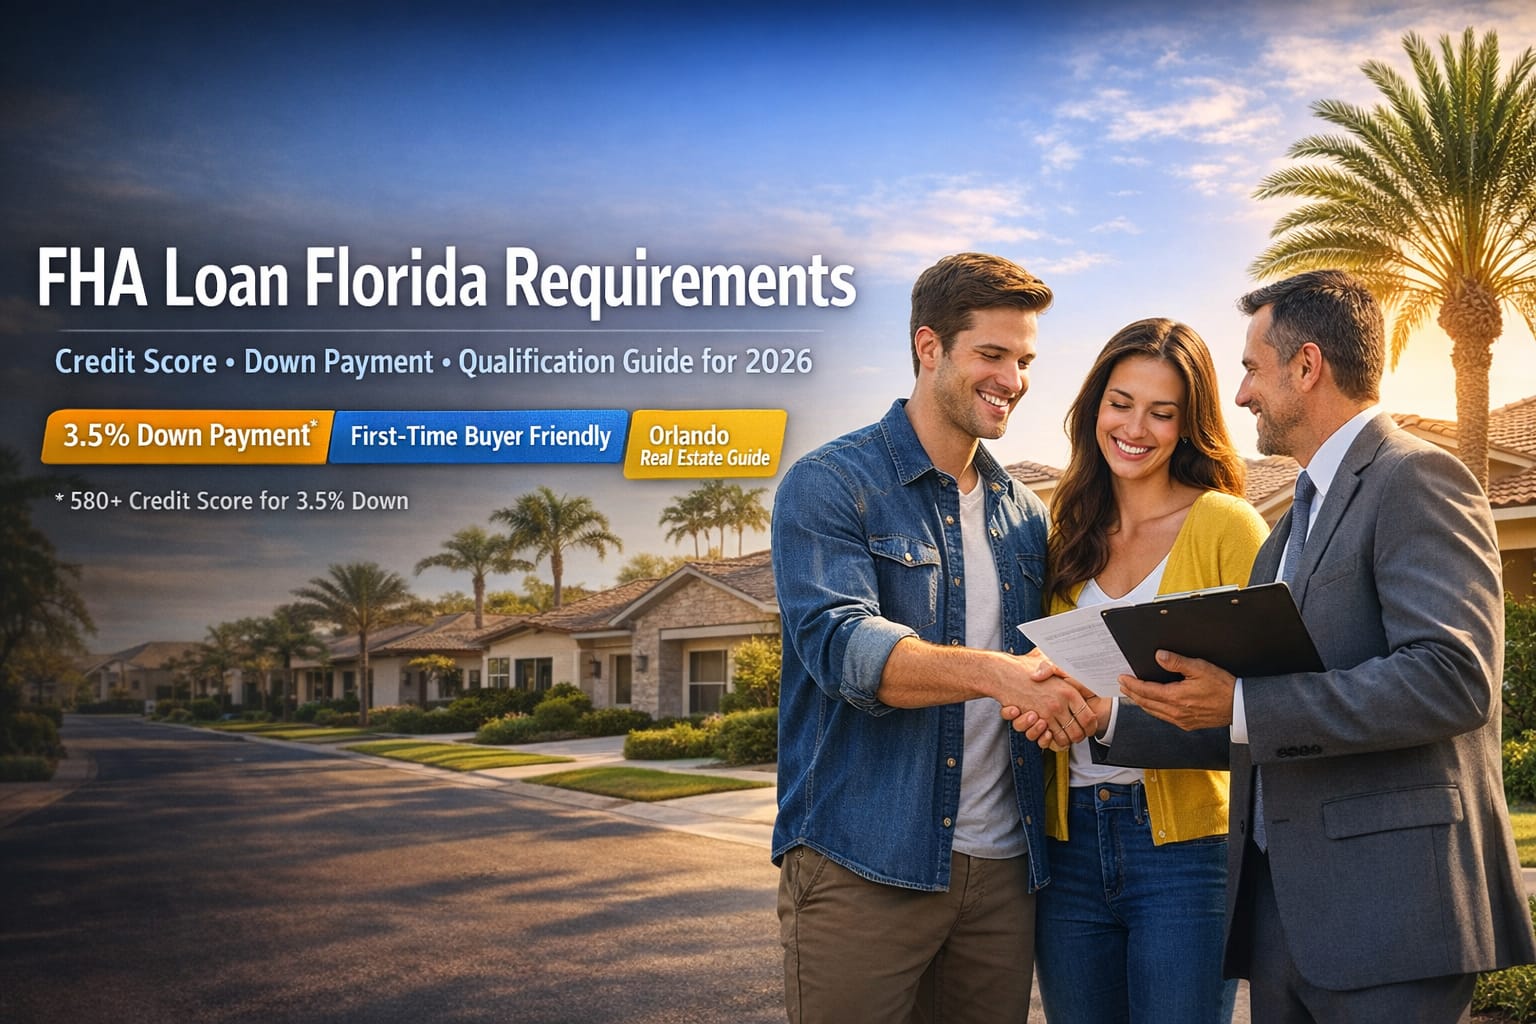
Quick Answer: FHA loan Florida requirements typically include a minimum 580 credit score for a 3.5% down payment, steady income, a manageable debt-to-income ratio, and a home that meets FHA property standards. Loan limits vary by county, and buyers must pay FHA mortgage insurance. These loans are popular with first-time homebuyers in Orlando.

What Is an FHA Loan?

An FHA loan is a mortgage backed by the Federal Housing Administration. The goal is simple: make homeownership more accessible.

Compared with conventional loans, FHA loans allow:

  • Lower credit scores
  • Smaller down payments
  • More flexible qualification standards

This is why FHA financing is extremely common among buyers purchasing their first home in Orlando.

If you’re planning to purchase property locally, reviewing a full Orlando home buying guide can also help you prepare.

FHA Loan Florida Requirements

To qualify for an FHA mortgage in Florida, buyers generally must meet several key requirements.

Requirement Typical FHA Guideline
Minimum Credit Score 580 for 3.5% down payment
Down Payment 3.5% minimum
Debt-to-Income Ratio Usually under 43%
Employment History 2 years stable income preferred
Primary Residence Home must be owner occupied
Mortgage Insurance Required for all FHA loans

These guidelines are national FHA standards, but loan limits and some qualification details vary in Florida depending on the county.

FHA Loan Credit Score Requirements

Your credit score plays a big role in FHA approval.

  • 580+ credit score → eligible for 3.5% down payment
  • 500–579 score → may require 10% down
  • 620+ → typically easier approval with lenders

Many buyers assume they need perfect credit to buy a home, but FHA loans are designed for buyers rebuilding credit or entering the market for the first time.

FHA Down Payment Requirements

The biggest reason buyers choose FHA financing is the low down payment.

With a 580 credit score, buyers can purchase a home with just 3.5% down.

For example:

  • $300,000 home → $10,500 down payment
  • $400,000 home → $14,000 down payment

In many cases, buyers can also receive help through Florida down payment assistance programs.

FHA Loan Limits in Florida

FHA loan limits change each year and vary by county.

For the Orlando area (Orange County), the FHA loan limit is typically aligned with national conforming limits.

You can confirm current limits through the HUD FHA loan limit lookup tool.

FHA Property Requirements

Not every home qualifies for FHA financing.

The property must meet FHA appraisal and safety standards, including:

  • Safe structure and foundation
  • Working electrical and plumbing
  • No significant roof damage
  • No major safety hazards

This protects buyers from purchasing homes with serious issues.

It’s also smart to watch for common problems buyers overlook. Here are the top red flags when buying a home.

Pros and Cons of FHA Loans

Advantages

  • Low down payment
  • Lower credit score requirements
  • Higher approval rates for first-time buyers
  • Flexible income qualifications

Disadvantages

  • Mortgage insurance is required
  • Loan limits may restrict price range
  • Property condition rules can be strict

Common FHA Loan Mistakes Buyers Make

  • Opening new credit cards before closing
  • Changing jobs during loan approval
  • Not budgeting for closing costs
  • Assuming any home will qualify for FHA

Many buyers also forget about additional expenses. Learn about the hidden costs of buying a home in Florida.

How FHA Loans Work in Orlando

In the Orlando real estate market, FHA loans are extremely common among first-time buyers and relocating families.

Many neighborhoods in the area fall within FHA loan limits, making them attractive options for buyers who want affordable monthly payments.

However, Orlando is competitive. Homes that qualify for FHA financing often receive multiple offers.

Understanding the local market — including how interest rates affect Orlando home prices — helps buyers make smarter decisions.

Step-by-Step FHA Loan Process

  1. Check your credit score
  2. Speak with an FHA-approved lender
  3. Get pre-approved
  4. Start house hunting
  5. Submit an offer
  6. FHA appraisal and underwriting
  7. Close on your home

Summary

FHA loan Florida requirements are designed to make homeownership more accessible. With flexible credit guidelines and a low down payment, FHA financing continues to help thousands of buyers purchase homes every year.

For Orlando buyers especially, FHA loans can be one of the fastest ways to enter the real estate market.

Work With an Orlando Real Estate Expert

If you’re considering buying a home using an FHA loan in Orlando, working with the right Realtor can make the entire process smoother.

At Orlando Realty Consultants, we help buyers navigate financing options, identify homes that qualify for FHA loans, and negotiate competitive offers.

Call or text 407-902-7750 to start your home search today.

Serving buyers across Orlando, Florida.

Se Habla Español.

Frequently Asked Questions

What credit score is needed for an FHA loan in Florida?

Most FHA loans require a minimum credit score of 580 to qualify for the 3.5% down payment program. Some lenders may allow lower scores with a larger down payment.

How much is the FHA down payment in Florida?

The minimum down payment is 3.5% if your credit score is 580 or higher.

Are FHA loans only for first-time buyers?

No. FHA loans are popular with first-time buyers but can also be used by repeat buyers purchasing a primary residence.

Do FHA loans require mortgage insurance?

Yes. FHA loans require both upfront mortgage insurance and monthly mortgage insurance payments.

What types of homes qualify for FHA loans?

Single-family homes, some condos, and certain townhomes may qualify if they meet FHA property standards.

Can FHA loans be used for investment properties?

No. FHA loans are only available for primary residences.

What are FHA loan limits in Orlando?

Loan limits change annually. Buyers can check current limits using HUD’s FHA loan limit tool.

How long does FHA loan approval take?

Most FHA loans close within 30–45 days depending on lender processing time.

Can closing costs be included in an FHA loan?

Closing costs usually cannot be rolled into the loan but may be paid by the seller or covered by assistance programs.

Is FHA financing common in Orlando?

Yes. FHA loans are widely used by first-time buyers in the Orlando housing market.

Let's Keep In Touch!

New ORC Form Lead

"*" indicates required fields

This field is for validation purposes and should be left unchanged.
TOC*

Do You Have to Be Behind to Do a Short Sale?

Do You Need To Miss Payments To Qualify for a Short Sale?

Quick Answer: No, you do not always need to miss payments to qualify for a short sale. While some lenders prefer borrowers to be behind, many will approve a short sale if you can prove financial hardship, declining home value, or inability to continue payments long term.

If you’re a homeowner in Orlando dealing with negative equity or financial pressure, this is one of the biggest misconceptions I hear. Let’s break it down clearly so you don’t make a costly mistake.

Understanding Short Sale Requirements

A short sale happens when your lender agrees to accept less than what you owe on your mortgage. This is typically done to avoid foreclosure, which is more expensive and time-consuming for the bank.

To qualify, lenders generally look at three key factors:

  • Financial hardship (job loss, income reduction, medical issues)
  • Negative equity (you owe more than the home is worth)
  • Inability to maintain payments long-term

Notice what’s NOT always required: missing payments.

Do You Actually Need to Be Behind on Payments?

Here’s the truth from real-world experience: some lenders prefer you to be behind, but it is NOT a universal requirement.

In fact, many homeowners in Orlando qualify for a short sale while still current — especially if they can show a clear financial hardship.

Scenario Short Sale Approval Likelihood
Current on payments + strong hardship High
1–3 months behind Very High
Severely delinquent High but risk of foreclosure increases

The key is documentation, not delinquency.

What Lenders Really Want to See

Lenders care more about your financial reality than whether you skipped payments. They want to know:

  • Are you facing a legitimate hardship?
  • Is your situation likely to improve?
  • Is foreclosure the alternative?

If the answer points toward financial distress, a short sale becomes a strong option.

How Short Sales Work (Step-by-Step)

  1. Evaluate your financial situation
  2. Gather hardship documentation
  3. List your home with a short sale specialist
  4. Receive an offer from a buyer
  5. Submit the package to your lender
  6. Negotiate with the bank
  7. Close and resolve the debt

If you’re unsure where to start, visit https://orlandorealtyconsultants.com/negative-equity-home-sale-florida/ for a deeper breakdown.

Pros and Cons of Missing Payments

Pros

  • May increase urgency with lender
  • Shows financial distress clearly

Cons

  • Damages your credit significantly
  • Triggers collection activity
  • Increases foreclosure risk
  • Adds late fees and penalties

Bottom line: don’t intentionally fall behind without a strategy.

Common Mistakes Homeowners Make

  • Waiting too long to explore options
  • Assuming you must stop paying first
  • Trying to handle the bank alone
  • Not documenting hardship properly
  • Ignoring foreclosure timelines

This is where having an experienced short sale agent matters — and honestly, it can make or break the outcome.

How It Works Specifically in Orlando, Florida

In Orlando, we’re seeing a mix of homeowners dealing with rising insurance costs, property taxes, and shifting market conditions.

Here’s what I’m seeing on the ground:

  • Lenders are more flexible than they were years ago
  • Short sales are still a viable foreclosure alternative
  • Timing is everything — waiting can limit your options

For local homeowners, working with someone who understands the Orlando market is critical. You can also review guidance from the https://www.consumerfinance.gov/ask-cfpb/what-is-a-short-sale-en-289/ for additional insight.

My Experience With Short Sales

I’ve been handling short sales in Central Florida for over 20 years. I’ve worked directly with lenders, negotiators, and distressed homeowners in every type of situation you can imagine.

Here’s the reality: every case is different. There is no one-size-fits-all answer, and that’s exactly why strategy matters.

FAQs About Missing Payments and Short Sales

Do I have to be behind on my mortgage to qualify?

No. Many lenders approve short sales based on hardship alone.

Will missing payments help my case?

Sometimes, but it can also hurt your credit and increase risk.

Can I do a short sale if I’m current?

Yes, especially if you can document financial hardship.

What counts as a hardship?

Job loss, divorce, medical issues, relocation, or income reduction.

How long does a short sale take?

Typically 60–120 days depending on lender response time.

Will a short sale hurt my credit?

Yes, but usually less than a foreclosure.

Can the bank deny my short sale?

Yes, if documentation is weak or value doesn’t support it.

Do I need a Realtor for a short sale?

Absolutely. Negotiation with the lender is complex.

What happens after a short sale?

You may be able to buy again in as little as 2–3 years.

Final Thoughts

You do NOT need to miss payments to qualify for a short sale — but you do need a clear plan.

The worst thing you can do is guess your way through this process or wait until foreclosure is knocking on your door.

Get Expert Help From Orlando Realty Consultants

If you’re dealing with negative equity or financial stress, let’s talk. I’ll walk you through your options honestly and help you avoid costly mistakes.

Orlando Realty Consultants
📞 407-902-7750
Serving Orlando, Florida
Se Habla Español

Start here: https://orlandorealtyconsultants.com/negative-equity-home-sale-florida/

Let's Keep In Touch!

New ORC Form Lead

"*" indicates required fields

This field is for validation purposes and should be left unchanged.
TOC*

Hidden Costs of Buying a Home in Florida

Quick Answer: The hidden costs of buying a home in Florida include closing costs, home insurance, property taxes, HOA fees, inspections, appraisals, and maintenance expenses. These costs can add thousands of dollars beyond the purchase price. Understanding them early helps buyers in Orlando avoid surprises and budget confidently.

Buying a home is exciting, especially in a market like Orlando, Florida. But many buyers focus only on the purchase price and mortgage payment. In reality, the true cost of homeownership includes several hidden costs of buying a home in Florida that can catch buyers off guard.

As an Orlando Realtor working with buyers every day, I’ve seen deals fall apart simply because someone didn’t understand the full financial picture. This guide breaks down the real costs so you can prepare properly and avoid surprises.

Hidden costs of buying a home in Florida explained by Orlando Realtor

What Are the Hidden Costs of Buying a Home in Florida?

The hidden costs of buying a home in Florida are expenses beyond the purchase price that buyers must pay during the purchase process or after they move in.

These costs commonly include:

  • Closing costs
  • Home inspections
  • Appraisal fees
  • Title insurance
  • Homeowners insurance
  • Property taxes
  • HOA fees
  • Moving expenses
  • Maintenance and repairs

In Florida, buyers typically spend 2%–5% of the home’s purchase price on closing-related expenses alone.

Typical Hidden Costs Florida Home Buyers Should Expect

Florida home buying closing costs breakdown chart
Cost Type Typical Cost in Florida When Paid
Closing Costs 2% – 5% of purchase price At closing
Home Inspection $350 – $600 During contract period
Appraisal Fee $500 – $800 Before loan approval
Title Insurance $1,000 – $2,500+ At closing
Homeowners Insurance $2,500 – $6,000 annually Before closing
Property Taxes Varies by county Escrowed with mortgage
HOA Fees $50 – $600+ monthly Monthly
Maintenance & Repairs 1% – 3% of home value annually Ongoing

1. Closing Costs in Florida

Closing costs are one of the biggest hidden costs of buying a home in Florida. These fees cover lenders, title companies, escrow services, and government recording charges.

Typical items include:

  • Lender origination fees
  • Title search
  • Title insurance
  • Recording fees
  • Escrow fees
  • Prepaid taxes

You can learn more about the full buying process in our Orlando home buying guide.

2. Florida Homeowners Insurance

Insurance is one of the most significant hidden costs Florida buyers face.

Because of hurricane exposure and rising insurance risks, premiums have increased significantly across the state.

Many Orlando buyers pay:

  • $2,500 – $6,000 per year
  • More for older homes or properties near water

For official insurance resources, visit the Florida Office of Insurance Regulation.

3. Property Taxes

Property taxes in Orlando vary depending on location, exemptions, and property value.

Many buyers underestimate how taxes increase after purchase if the previous owner had a homestead exemption.

You can estimate taxes using tools from the Orange County Property Appraiser.

4. HOA Fees

Many Orlando communities have homeowners associations.

HOA fees may include:

  • Community maintenance
  • Security gates
  • Pools and amenities
  • Lawn care

Fees can range from $50 to over $600 per month.

5. Home Inspections

A professional home inspection protects buyers from major surprises.

Common inspections in Florida include:

  • General home inspection
  • Wind mitigation inspection
  • 4-point inspection
  • Termite inspection

6. Maintenance and Repairs

Homeownership always comes with maintenance.

A good rule is to budget 1%–3% of the home’s value annually for upkeep.

For a $400,000 Orlando home, that’s $4,000–$12,000 per year.

Practical Checklist for Buyers

  • Get a detailed loan estimate from your lender
  • Budget 3%–5% for closing costs
  • Request insurance quotes early
  • Review HOA rules and fees
  • Set aside an emergency repair fund

Common Mistakes Buyers Make

  • Underestimating insurance costs
  • Not accounting for HOA fees
  • Ignoring maintenance costs
  • Skipping inspections
  • Overextending their budget

If you’re researching homes in Orlando, our article on top red flags when buying a home is also helpful.

How These Costs Affect Orlando Buyers

In the Orlando real estate market, many buyers are relocating from other states where costs may be structured differently.

Here are a few Orlando-specific realities:

  • Insurance premiums have increased statewide
  • Many communities include HOA fees
  • Property taxes reset after purchase
  • Maintenance costs are higher due to humidity and storms

Understanding these factors helps buyers make smarter decisions when purchasing in Central Florida.

Pros and Cons of Buying a Home in Florida

Pros

  • No state income tax
  • Strong housing demand
  • Great climate and lifestyle
  • Long-term appreciation potential

Cons

  • Higher insurance costs
  • HOA prevalence
  • Maintenance from weather exposure

Summary

The hidden costs of buying a home in Florida can add thousands of dollars to your purchase. From insurance and closing costs to HOA fees and maintenance, understanding the full financial picture is essential.

Prepared buyers make better decisions, avoid surprises, and feel confident about their investment.

Work With an Orlando Expert

If you’re thinking about buying a home in Orlando, working with a knowledgeable local Realtor makes the process much easier.

At Orlando Realty Consultants, we help buyers understand every cost involved before they make an offer.

Whether you’re a first-time buyer, relocating, or investing, we’ll guide you through the process step by step.

Call or text 407-902-7750 to start your home search.

Se habla español.

Frequently Asked Questions

What are the hidden costs of buying a home in Florida?

Hidden costs include closing costs, insurance premiums, property taxes, HOA fees, inspections, and ongoing maintenance expenses.

How much are closing costs in Florida?

Closing costs typically range from 2% to 5% of the purchase price depending on lender fees, title services, and prepaid expenses.

Why is Florida home insurance so expensive?

Insurance costs are higher due to hurricane risk, rebuilding costs, and changes in the insurance market across the state.

Do buyers pay title insurance in Florida?

In many Florida counties, the seller traditionally pays for the owner’s title policy, but buyers may still pay lender title insurance.

Are HOA fees common in Orlando?

Yes. Many Orlando communities have HOAs that maintain amenities, landscaping, and neighborhood standards.

How much should I budget for home maintenance?

Most homeowners budget 1%–3% of the home’s value annually for maintenance and repairs.

Can hidden costs affect mortgage approval?

Yes. Lenders consider insurance, taxes, and HOA fees when calculating your debt-to-income ratio.

Are inspections required in Florida?

Inspections are not legally required but strongly recommended to protect buyers from costly surprises.

How can buyers reduce closing costs?

Negotiating seller concessions and comparing lenders can sometimes reduce the amount buyers pay at closing.

Should I work with a local Orlando Realtor?

Yes. A local expert understands neighborhood fees, insurance issues, and market conditions specific to Central Florida.

Let's Keep In Touch!

New ORC Form Lead

"*" indicates required fields

This field is for validation purposes and should be left unchanged.
TOC*

How Interest Rates Affect Home Prices in Orlando, FL

If you are trying to figure out whether now is a smart time to buy or sell in Orlando, interest rates need to be part of the conversation. They do not control the market by themselves, but they absolutely affect affordability, demand, negotiating power, and how quickly homes move.

Quick Answer: Interest rates affect home prices in Orlando by changing what buyers can afford each month. When rates rise, borrowing costs go up, buyer demand often cools, and price growth may slow. When rates fall, affordability improves, demand can increase, and home prices often face stronger upward pressure, especially when inventory is tight.

That said, Orlando is not a one-size-fits-all market. A higher-rate environment does not always mean prices will drop, and lower rates do not guarantee easy deals. Local inventory, job growth, migration, and neighborhood demand all matter. In plain English: rates influence prices, but they do not act alone.

If you are looking for guidance tailored to Orlando homes for sale, this page breaks down what is really happening and what buyers, sellers, and investors should watch.

Why Interest Rates Matter So Much in Real Estate

Mortgage interest rates directly impact monthly housing costs. Even if the purchase price stays the same, the payment can change a lot when rates move.

That matters because most buyers shop based on monthly affordability, not just sticker price. When rates go up:

  • Monthly payments increase
  • Buying power drops
  • Some buyers lower their budget
  • Some buyers pause their search
  • Competition may ease on certain listings

When rates go down, the opposite usually happens:

  • Monthly payments improve
  • More buyers qualify
  • Demand often increases
  • Competition can heat up fast
  • Home prices may face more upward pressure

This is why people searching for “How Interest Rates Affect Home Prices in Orlando” are asking the right question. Rates shape affordability first, and affordability shapes demand. Demand is a major driver of pricing.

How Interest Rates Affect Home Prices in Orlando: The Core Explanation

Here is the cleanest way to understand it:

  1. Rates rise. Buyers can afford less house for the same monthly payment.
  2. Demand softens. Some buyers step back, reduce budget, or ask for concessions.
  3. Price growth may slow. Sellers may need to price more carefully.
  4. Rates fall. Buyers gain purchasing power.
  5. Demand increases. More buyers compete for available homes.
  6. Prices can rise faster. This is especially true when inventory is limited.

But here is the part many articles miss: in Orlando, price movement depends heavily on the neighborhood, property type, and supply level. A well-priced home in a desirable area can still sell quickly even when rates are higher. On the flip side, an overpriced home can sit even if rates improve.

Table: What Usually Happens in Different Rate Environments

Rate Environment Buyer Behavior Seller Impact Likely Price Effect
Rates rising Buyers become more payment-sensitive and may reduce budget Sellers may need better pricing and more flexibility Price growth often slows or levels off
Rates stable Buyers adjust expectations and shop more strategically Sellers can plan with more confidence Prices often stabilize based on inventory and demand
Rates falling More buyers re-enter the market and competition increases Sellers may see stronger traffic and better terms Prices often face upward pressure

Key Concepts Buyers and Sellers Need to Understand

1. Buying Power Changes Faster Than Most People Expect

A one-point rate change can shift monthly payments enough to change what neighborhood or property type a buyer targets. That is why many buyers in Orlando move from detached homes to townhomes, from newer homes to resale homes, or from one part of Greater Orlando to another when rates move higher.

2. Affordability Impacts Demand

When fewer buyers can comfortably afford payments, demand can cool. That does not always crash prices, but it often reduces the kind of aggressive bidding wars Orlando saw in lower-rate periods.

3. Inventory Matters Just As Much

If inventory stays tight, home prices can remain surprisingly firm even with higher mortgage rates. Limited supply can keep values supported, especially in strong Orlando submarkets.

4. Seller Concessions Become More Important

In a higher-rate market, sellers may need to offer closing cost help, repair credits, or temporary rate buydowns. That can help a deal come together without a major price drop.

5. Orlando Is Not One Market

Downtown Orlando, Lake Nona, Winter Park, Dr. Phillips, College Park, Horizon West, and surrounding areas all behave differently. The relationship between rates and pricing is local, not just national.

Practical Guidance for Buyers

If you are buying in Orlando, do not obsess over headline rates and ignore the bigger picture. Focus on strategy.

  • Get fully pre-approved early. Know your real budget, not your guess.
  • Shop based on total payment. Include taxes, insurance, HOA, and maintenance.
  • Compare neighborhoods realistically. A payment-friendly area may outperform your first choice on overall value.
  • Ask about rate buydowns. A seller concession can make more difference than a small price cut.
  • Think long term. If the home works for your life and budget, waiting for the “perfect” rate can backfire.
  • Review loan options carefully. Fixed, FHA, VA, conventional, and down payment assistance programs each affect affordability differently.

You should also review trusted consumer resources like CFPB home buying guidance and track general mortgage movement through sources like Freddie Mac’s mortgage market survey.

For local planning, it also helps to read our what buyers should know this year guide and our top red flags when buying a home article.

Practical Guidance for Sellers

If you are selling in a higher-rate market, pricing discipline matters more than wishful thinking.

  • Price based on current demand, not old headlines.
  • Make the home show-ready. Buyers are pickier when payments are higher.
  • Be open to concessions. Helping with closing costs or a buydown can widen your buyer pool.
  • Watch days on market. The longer a listing sits, the weaker your negotiating position usually gets.
  • Understand your competition. Active inventory matters more than closed sales alone.

If you are debating timing, read our home valuation in Orlando resources and selling a home during hurricane season guide for added local perspective.

Pros and Cons of Buying or Selling in a Higher-Rate Market

Pros

  • Less buyer frenzy than ultra-low-rate periods
  • More room for negotiation in some price points
  • Greater chance of inspection and financing contingencies being accepted
  • Potential refinance opportunity later if rates improve

Cons

  • Higher monthly payments
  • Reduced affordability
  • Stricter lender qualification pressure
  • Sellers may need to accept slower activity or more concessions

Common Mistakes to Avoid

  • Waiting for rates to crash. Nobody times the market perfectly, and falling rates can bring more competition.
  • Ignoring total monthly cost. Taxes, insurance, HOA fees, and repairs matter.
  • Overpricing a listing. Buyers notice fast, especially when payment pressure is high.
  • Assuming all Orlando neighborhoods move the same way. They do not.
  • Skipping local advice. National headlines rarely tell you what is happening street by street in Orlando.

How It Works in Orlando

Orlando has some built-in strengths that can keep housing demand more stable than people expect. It continues to attract buyers relocating for jobs, lifestyle, education, and long-term growth. At the same time, affordability is a real issue, especially when mortgage rates remain elevated compared with the 2020 to 2021 period.

Here is what that means locally:

  • Move-up buyers feel the lock-in effect. Some owners stay put because they do not want to trade a low existing mortgage rate for a much higher one.
  • That can keep resale inventory tighter. Less inventory can support prices.
  • Payment-sensitive buyers become more selective. Homes that need work or are priced too aggressively can sit.
  • Well-located, well-presented homes still move. Especially in desirable Orlando neighborhoods.
  • Investors run tighter numbers. Higher financing costs can reduce cash flow, which affects what investors are willing to pay.

For investors, the smart move is to underwrite conservatively and not rely on appreciation alone. If that is your focus, our short term rental investing in Orlando article is worth reading.

You can also review broader market context from Orlando Regional REALTOR® Association market reports, Redfin Orlando housing trends, and Zillow Orlando home values.

Simple Orlando Buyer Checklist in a Higher-Rate Market

  1. Get pre-approved with a lender before touring seriously.
  2. Set a monthly payment ceiling and stick to it.
  3. Compare at least two or three loan scenarios.
  4. Target homes with value, not just trendiness.
  5. Ask about seller-paid concessions and rate buydowns.
  6. Review insurance costs carefully in Florida.
  7. Work with a local agent who knows Orlando neighborhood pricing.

Bottom Line

How interest rates affect home prices in Orlando comes down to affordability, demand, and supply. Higher rates usually reduce buying power and can slow price growth. Lower rates usually improve affordability and can push demand and prices higher. But in Orlando, inventory levels, neighborhood strength, and property condition still play a huge role.

The truth is simple: rate changes matter, but they are not the whole story. If you make decisions based only on headlines, you can miss good opportunities. If you look at the full local picture, you make better moves.

Work With Orlando Realty Consultants

If you want straight answers about buying, selling, or investing in Orlando, Florida, Orlando Realty Consultants is here to help. We work with buyers, sellers, and investors who want real local guidance, not fluff.

Need help figuring out whether today’s rate environment makes sense for your next move? Call Orlando Realty Consultants at 407-902-7750. We can help you understand your options, evaluate neighborhoods, and build a strategy that fits your budget and goals. Se Habla Espanol.

Frequently Asked Questions

Do higher interest rates always lower home prices in Orlando?

No. Higher rates often reduce affordability and slow demand, but prices do not always fall. If inventory stays limited in Orlando, prices can remain stable or even rise in strong neighborhoods.

Will home prices in Orlando go up if mortgage rates drop?

They often can. Lower rates improve buying power, which usually brings more buyers into the market. If listings stay limited, that added demand can push prices higher.

Is it better to buy now or wait for lower rates?

That depends on your finances, timeline, and the home you need. Waiting for lower rates can mean more competition and higher prices. Buying now may offer more negotiating room, and refinancing later may be possible.

How do rising rates affect first-time home buyers in Orlando?

First-time buyers usually feel the biggest squeeze because they are more payment-sensitive. Higher rates can reduce buying power, increase monthly costs, and make budgeting tighter.

Do interest rates affect sellers too?

Absolutely. Higher rates reduce some buyers’ purchasing power, which can lead to fewer offers, more concessions, and more pricing pressure for sellers.

Can Orlando home prices still rise in a high-rate market?

Yes. If demand remains solid and inventory stays tight, prices can still increase even when rates are elevated. Orlando is not immune to rate pressure, but it also is not a market that moves only on rates.

What matters more in Orlando: interest rates or inventory?

Both matter, but inventory often explains why prices do not fall as much as buyers expect. When there are not enough homes for sale, pricing can stay firmer even with higher borrowing costs.

How do investors view higher rates in Orlando?

Most investors become more selective. Higher financing costs can shrink cash flow and lower acceptable purchase prices, especially on properties that already have thin margins.

Should buyers focus only on mortgage rate headlines?

No. Buyers should look at the total picture: home price, insurance, taxes, HOA fees, seller concessions, neighborhood demand, and long-term affordability.

Who should I talk to about buying or selling in Orlando right now?

Start with a local Orlando real estate professional who understands neighborhood-level trends and a lender who can break down your real monthly options. That combination gives you the clearest picture.

Let's Keep In Touch!

New ORC Form Lead

"*" indicates required fields

This field is for validation purposes and should be left unchanged.
TOC*

Short Sale vs Foreclosure: Orlando Seller Guide

Short Sale vs Foreclosure: What Orlando Homeowners Need to Know

Quick Answer: A short sale allows you to sell your home for less than what you owe with lender approval, helping you avoid foreclosure and reduce credit damage. Foreclosure happens when the lender takes your home after missed payments. In most cases, a short sale is the better option if you act early.

If you’re behind on payments or starting to feel financial pressure, you’re not alone. I’ve worked with homeowners across Orlando for over 20 years helping them navigate tough situations like this—and the biggest mistake I see is waiting too long.

Let’s break this down clearly so you understand your options and what actually makes sense for your situation.

What Is a Short Sale?

A short sale happens when your lender agrees to let you sell your home for less than what you owe on your mortgage. The lender takes a loss, but it’s usually less costly for them than a foreclosure.

  • You stay in control of the sale
  • Your credit is impacted—but less severely
  • You may qualify to buy again sooner
  • You avoid the public stigma of foreclosure

What Is Foreclosure?

Foreclosure is when the lender takes legal action to repossess your home after missed payments. In Florida, this is a judicial process, meaning it goes through the courts.

  • You lose control of the process
  • Severe credit damage (can drop 150–300+ points)
  • Public record and long-term financial impact
  • Possible deficiency judgment

Short Sale vs Foreclosure: Key Differences

Factor Short Sale Foreclosure
Control You sell the home Lender takes property
Credit Impact Moderate Severe
Future Home Buying 2–4 years 5–7 years
Public Record Less visible Public foreclosure filing
Emotional Stress Manageable High

How the Process Works (Step-by-Step)

Short Sale Process

  1. Contact an experienced short sale agent
  2. Submit hardship package to lender
  3. List and market the property
  4. Receive and negotiate offers
  5. Lender approves sale
  6. Close the transaction

Foreclosure Process

  1. Miss payments
  2. Lender files lawsuit
  3. Court process begins
  4. Judgment entered
  5. Property auctioned
  6. Eviction possible

Pros and Cons

Short Sale Pros

  • Less credit damage
  • More control
  • Potential relocation assistance
  • Avoid foreclosure stigma

Short Sale Cons

  • Requires lender approval
  • Can take time
  • Documentation-heavy

Foreclosure Cons (Reality Check)

  • Major credit damage
  • Loss of control
  • Public record
  • Harder to recover financially

Common Mistakes Homeowners Make

  • Waiting too long to take action
  • Talking only to the bank instead of a professional
  • Hiring an agent with no short sale experience
  • Ignoring lender notices

How It Works in Orlando, Florida

In Orlando and Central Florida, lenders are generally open to short sales—but timing is everything. Once foreclosure is filed, your options shrink quickly.

Working with an experienced local agent who understands lender negotiation is critical. This isn’t a typical real estate transaction—it’s a specialized process.

For official foreclosure timelines and consumer protection guidance, visit: Consumer Financial Protection Bureau

Watch: Not Every Agent Understands Short Sales

What Should You Do Next?

If you’re even thinking about foreclosure, don’t wait. The earlier you act, the more options you have.

I’ve been helping homeowners with short sales for over 20 years right here in Orlando. I know how to negotiate with lenders, structure deals, and guide you through this step-by-step.

Call Orlando Realty Consultants Today

Orlando Realty Consultants
📞 407-902-7750
Serving Orlando, Florida

We offer confidential consultations and real solutions. If you think you may need a short sale, don’t wait until it’s too late.

Se Habla Español

Frequently Asked Questions

Is a short sale better than foreclosure?

Yes, in most cases a short sale causes less damage to your credit and allows you to recover faster.

How long does a short sale take?

Typically 60–120 days depending on the lender and documentation.

Can I stay in my home during a short sale?

Yes, you usually remain in the home until closing.

Do I need to be behind on payments?

Not always, but you must show financial hardship.

How much does my credit drop?

Short sales impact credit less than foreclosure, but it still depends on your situation.

Can the bank still come after me?

In some cases, but many short sales include deficiency waivers.

What happens after foreclosure?

The home is sold at auction, and you may face eviction.

Can I buy another home after a short sale?

Yes, often within 2–4 years depending on loan type.

Is foreclosure public record?

Yes, foreclosure filings are public and can impact future opportunities.

Who should I contact first?

Start with an experienced short sale agent—not just your lender.

Let's Keep In Touch!

New ORC Form Lead

"*" indicates required fields

This field is for validation purposes and should be left unchanged.
TOC*